
-
 Bank Ranking
Banks Ratios
Cement Statistics
Cement Ranking
Cement Ratios
Monetary and Economic Statistics
Oil, Gas and Fuel
Macro Economy
Consumer Spending
Inflation
Exports & Imports
Food Prices
Non Food Prices
Construction Materials
Petrochem. Ranking
Petrochem. Ratios
Retail Rankings
Retail Ratios
Grocery Ranking
Grocery Ratios
Top Growth
Dividend History

Saudi Arabia opens real estate VAT refund claims

 AI Summary

Content Summary: 
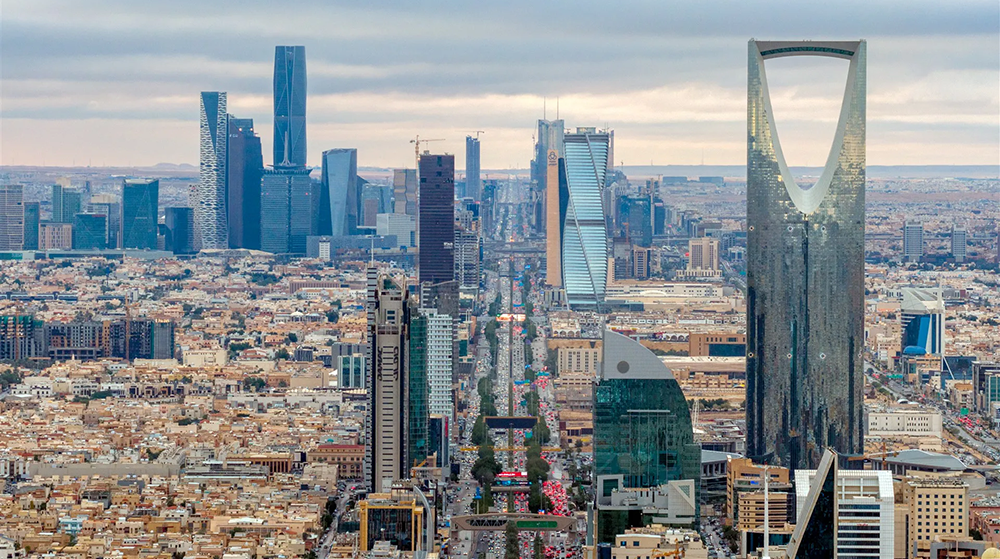
Riyadh city
The General Secretariat of the Zakat, Tax and Customs Committees (GSTC) recently announced that it has begun accepting applications to register claims for value-added tax (VAT) refunds on real estate supplies made by individuals between Jan. 1, 2018, and Oct. 4, 2020.
Applications must be submitted within 30 days of the publication of the relevant mechanisms and procedures in the Official Gazette, which took place on Oct. 13.
The amounts eligible for VAT refunds on certain real estate supplies made by individuals in Saudi Arabia could reach several SAR billions, according to Deloitte estimates in exclusive comments to Argaam.
The development has raised questions over who is entitled to receive the refunds, how they will be processed, and the legal implications for the relationship between property sellers and buyers.
Specialists told Argaam that the refund process extends beyond tax matters to encompass financial and civil rights between parties to real estate transactions.
This is particularly relevant in cases where buyers bore the VAT as part of the property purchase price, while sellers collected the tax and remitted it to the Zakat, Tax and Customs Authority (ZATCA).
Eligibility requirements stipulate that the real estate supply must have been made by an individual (a natural person) who remitted the VAT on the transaction to ZATCA.
The individual must also be proven not to have engaged in real estate activities involving the continuous and regular sale of properties for income-generating purposes.
Individuals who carried out more than one real estate supply over any consecutive 12-month period, with the aggregate value exceeding the mandatory VAT registration threshold under the Unified VAT Agreement for the Cooperation Council for the Arab States of the Gulf (GCC), are not eligible for refunds.
Deloitte: refunds could reach several SAR bln
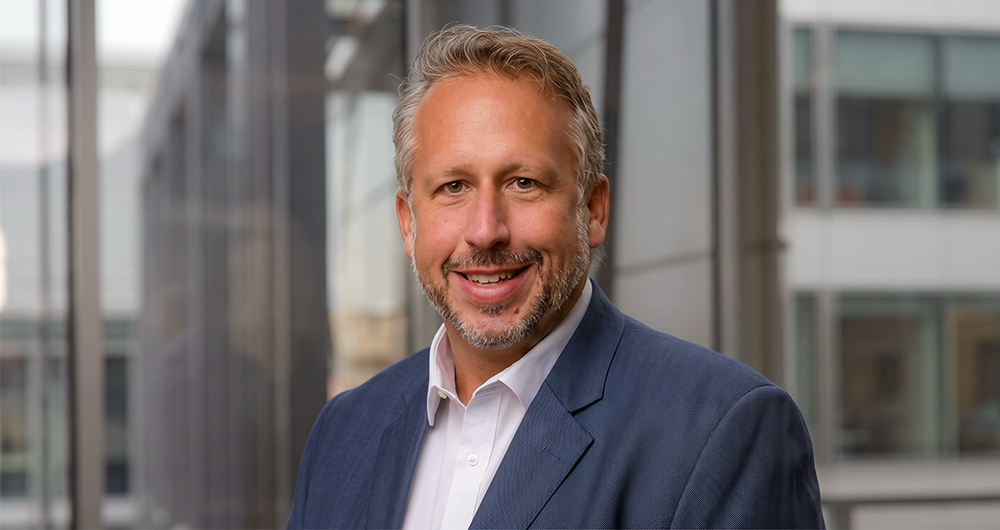
Michael Camberon, Deloitte Middle East’s indirect tax services leader and a senior executive director
Michael Camberon, Deloitte Middle East’s indirect tax services leader and a senior executive director, said the total amounts eligible for refunds are likely to reach several SAR billions over the entire period covered by the initiative.
In exclusive comments to Argaam, Camberon said data from the Housing Observatory and Data Center for Q1 2021 showed that more than 255,000 residential real estate transactions were recorded in Saudi Arabia in 2020.
The average value of transactions involving the sale of houses, apartments and villas ranged from around SAR 250,000 to SAR 900,000 per transaction. Meanwhile, the average value of land plot sales stood at approximately SAR 820,000.
Based on these figures, the total amounts eligible for refunds are likely to reach several billion riyals over the entire period in question, he said.
Higher-value transactions are expected to generate larger refunds. Individuals who completed multiple eligible sales may also be entitled to higher aggregate refunds, subject to the rules governing the number and value of transactions.
Limited economic impact expected
On the potential impact of the refunds on individual liquidity and the real estate market, Camberon said demand for refund applications is likely to be relatively limited.
This reflects the considerable time elapsed since the transactions were completed and the narrow window available for submitting claims. Accordingly, the overall macroeconomic impact is expected to remain modest.
He added that the scale of the impact would also depend on the time required to process applications and how beneficiaries choose to deploy the refunded amounts.
If the funds are reinvested in the real estate sector, they could provide a short-term boost to market activity.
They may also improve individual liquidity and support consumption or real estate activity, he said.
Challenges in establishing eligibility
Camberon said applicants will be required to submit documents substantiating eligible sales transactions, payment of VAT and penalties, as well as the relevant tax returns.
Verifying eligibility could prove more challenging due to difficulties in retrieving documentation for older transactions and multiple property sales within a 12-month period.
Other challenges include previous input tax deductions and determining whether the sales constituted a regular commercial activity.
He added that the initiative could allow eligible amounts previously paid to be recovered, potentially helping resolve certain outstanding matters.
However, disputes could also arise over eligibility, supporting documentation or the amounts due for refund.
Camberon stressed the importance of reviewing the applicable procedures and submitting complete applications within the specified deadline.
Recovering these amounts could prove difficult in practice unless the supporting documents and records are complete and well organized, he noted.
Who actually receives the refund?
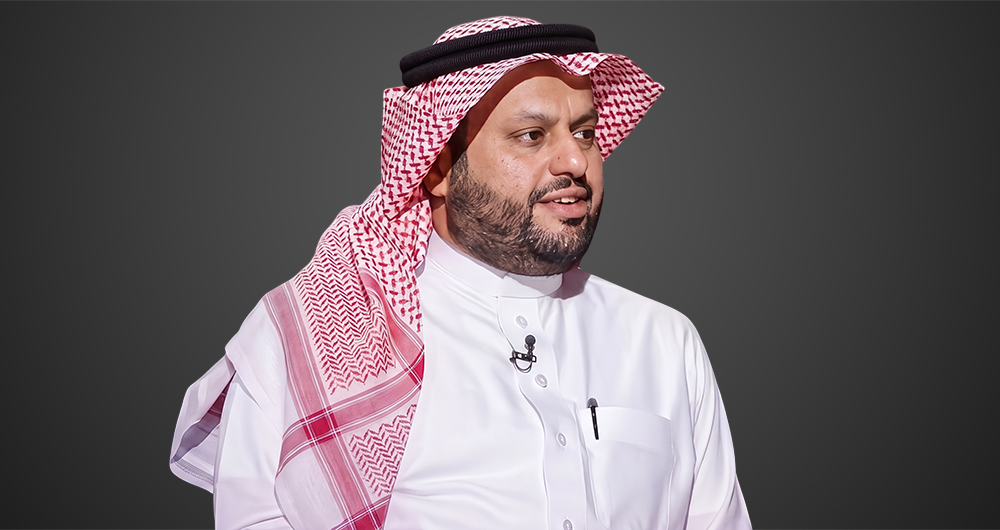
Abdullah Al-Baradi, a lawyer at Abdullah Al-Baradi Law Firm and Consultants
From a legal perspective, Abdullah Al-Baradi, a lawyer at Abdullah Al-Baradi Law Firm and Consultants, said the seller would be obligated to return the VAT refund to the buyer if the seller receives the amount from the authority.
This applies where the buyer originally bore the tax as part of the property’s purchase price, while the seller’s role was limited to collecting and remitting it.
In a phone interview with Argaam, Al-Baradi explained that if the seller refuses to voluntarily return the amount, the buyer may be entitled to file a claim for unjust enrichment.
The buyer could seek recovery of the amount received by the seller at the buyer’s expense, depending on the circumstances of each case.
He said this is based on Article 144 of the Civil Transactions Law, which addresses unjust enrichment without lawful grounds at another party’s expense.
Compensation is limited to the extent of the enrichment gained and the loss incurred by the other party.
Failure to apply for a refund on time could trigger compensation claims
Al-Baradi added that if the seller refuses to submit a refund application or fails to do so within the prescribed deadline, the buyer may have the right to seek compensation.
This would depend on the circumstances of each case and the damages resulting from the lost opportunity to recover the amount.
He explained that the seller’s failure to take the necessary steps within the deadline could constitute an actionable fault giving rise to compensation, provided that the damage and causal link are established.
He cited Article 120 of the Civil Transactions Law, which stipulates that anyone whose fault causes harm to another party is obligated to provide compensation.
This legal avenue is distinct from the official refund claim process before the committees.
Under the official procedures, the refund application must be submitted by the individual who remitted the VAT to the authority and meets the eligibility requirements.
A buyer’s claim against the seller, where the buyer economically bore the tax, instead concerns the legal relationship between the two parties to the transaction.
Comments {{getCommentCount()}}
Be the first to comment
رد{{comment.DisplayName}} على {{getCommenterName(comment.ParentThreadID)}}
{{comment.DisplayName}}
{{comment.ElapsedTime}}


Comments Analysis: